What is the state of the market?
It has to be one of, if not the first question, that we often encounter with new teams and leaders considering building for themselves instead of others. Our thoughts are below:
In this article
Writing this in 2022 we certainly are living through odd times. Having only just started to create certainty following the start of Brexit, we sailed straight into the largest global pandemic in the last 100 years and now seem to be charting a path into the most significant military intervention since World War Two. With all of those facts laid out it would seem entirely counterintuitive to observe the M&A market post in 2021 record levels of M&A activity – at the same time as Private Equity dry-powder peaked yet higher than it has in history.
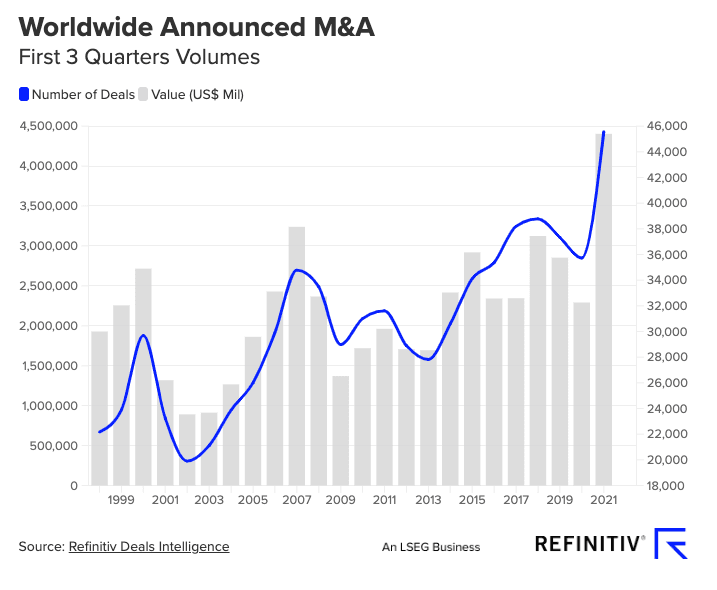
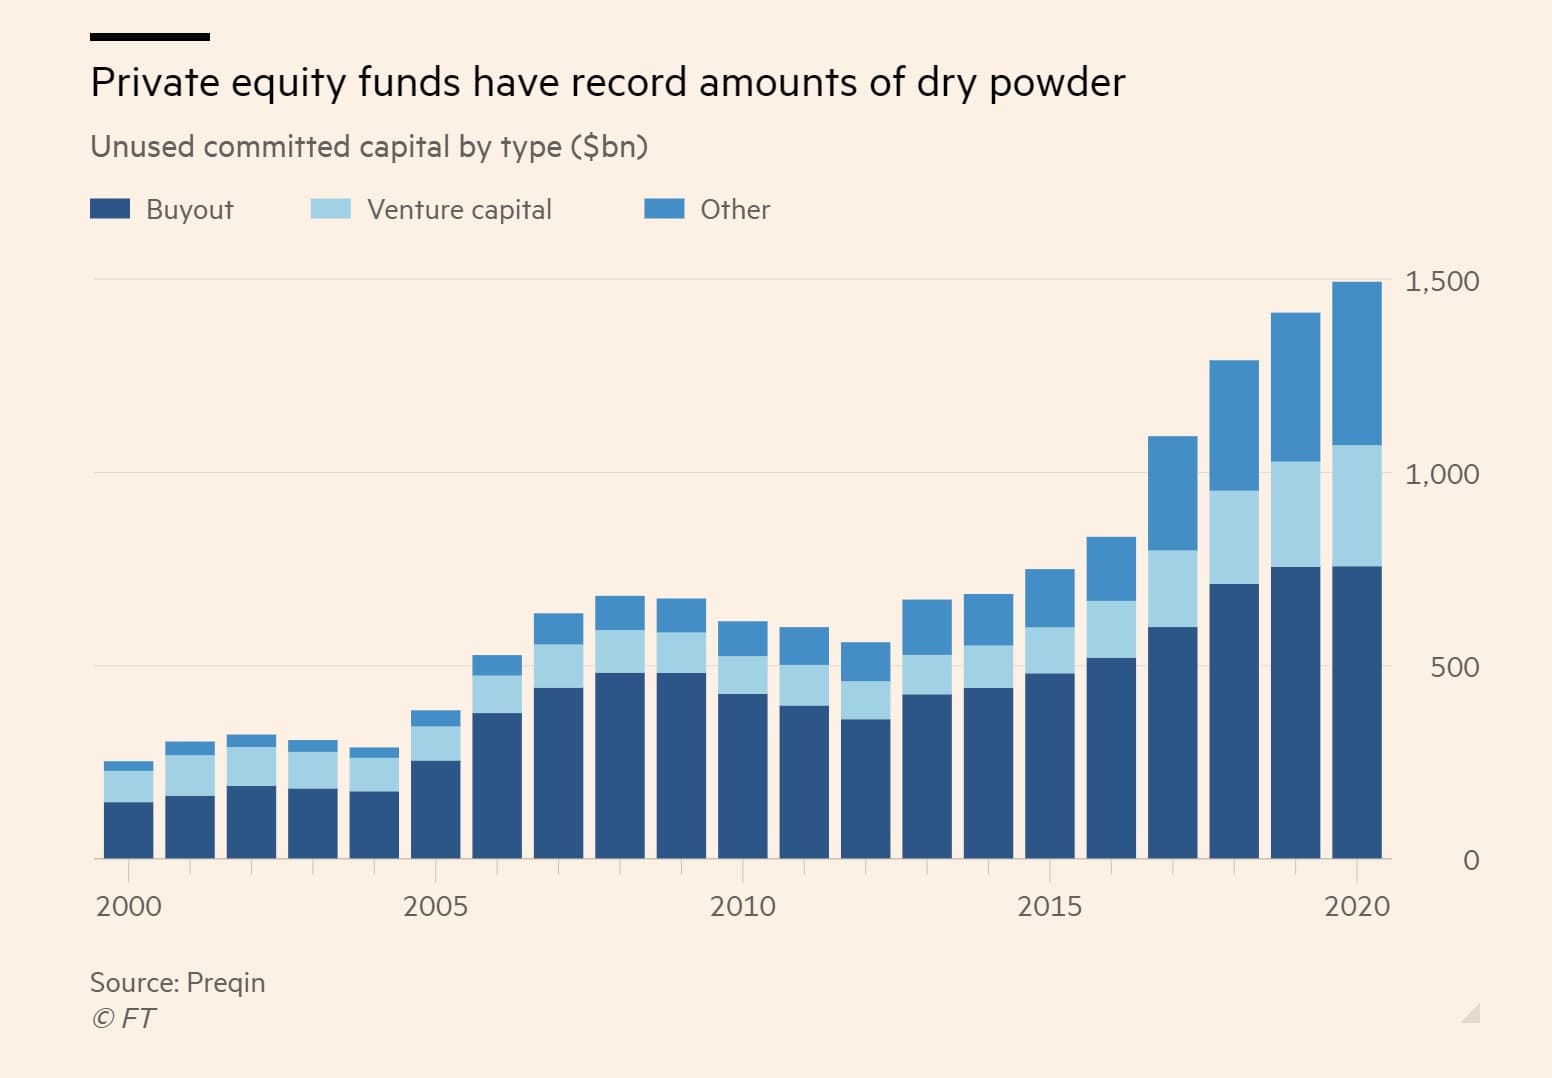
Whilst the the financial markets show volatility they are certainly less relevant to almost not relevant to most management teams, unless teams are considering listing/de-listing as part of your strategy. Whereas the M&A market & liquidity is entirely relevant because anyone looking to build a group would hope for an active deal market, rich with opportunities to feast on. Most would simply assume that during times of uncertainty M&A slows down when in fact often the opposite is true; change (in either direction) often yields transactional opportunities – its stable, benign environments which lead to fallow times for dealmaking. In this instance, we arguably have a once-in-a-generation level of uncertainty, which has (and will continue) to draw to market more business owners looking to de-risk rather than batten down the hatches for another term.
Notwithstanding the above, at Independence we believe in three dealmaking constants:
- Research reaps rewards over reacting
- Making the market market beats the market
- Leading with expertise
Research reaps rewards over reacting
95% of the deals we do at Independence are off-market (i.e they are not actively being listed and marketed to buyers), we do that through our unique approach to prospecting which is underpinned by data, research, technology and by mining the experience and thoughts of our mgmt teams.
In 2022, we have greater access to information than any generation before us and with more tools and capability to interrogate that data than ever before too. Whilst daunting for many, one added advantage of prospecting from a blank piece of paper is that process can heavily inform the buy-side strategy of that group because management are now connected with Science Fact instead of building from Science Fiction.
That very process of exploration allows management to also better calibrate their appetite to pursue their buy-build. Before having conducted any research it can be difficult to picture the scale of the opportunity – what’s out there, what’s realistic to acquire, what’s necessary in order to transact and what will the risk/rewards look like over time? Without research all of that is just speculation and who ever made a life changing decision based on just that? We take control of the facts and turn that into opportunity.
Making the market beats the market
With the M&A market so buoyant, many would be forgiven for thinking that simply plumbing into the sell-side advisory market is the answer to building quickly but that’s a flawed strategy. On-market deals are competitive, we are pitted against buyers who maybe more prolific than us as well as tethering ourselves to a process which we cannot control. Competition only ever helped a seller, so let’s treat that as the complimentary plan B to our Plan A off-market prospecting.
A benefit of the Independence process is that through continued prospecting in this manner we have an iteratively improved process each time it is run and voluminous direct contact with business owners – giving us a real-time view updated in perpetuity. The more time we run it the more data we sweep up, the more data we sweep up the better informed our research, the better informed our research the greater relevance we can create with our outreach to sellers and the better traction we have with business-owners and their advisors. On any typical outreach strategy we expect that funnel (which may have started with thousands of names) to yield dozens of active conversations, allowing us/the buyer to benefit from choice & competition – sellers actively vying for the opportunity to work with a best in class team who have done it before in their very own sector. A buyers dream either to work with or pass the baton over to without fear or regret.
Leading with expertise
By leading with exceptional management first, when we are speaking to vendors we are talking operator-to-operator. This allows us to understand the opportunity in more detail than anyone else could and encourages all parties to build faith and confidence in each other. A traditional marketed process led by someone else almost actively encourages distance between buyer and seller.
Without a firm process or prescriptive deal shape curbing how and when we can operate, we have the capacity to define the most appropriate structure and timing to suit the needs of both buyer and seller. This has to be the optimal outcome for everyone.
Summary
So next time someone asks “what is the state of the market?” I might relay exactly the same points or I may steer them to an Independence client, who will likely say “why does the market matter….we make our market and Independence Capital have the experience, process and resources to make that work for everyone”