Article 15

GREAT Britain

Why overseas capital is acquiring underpriced UK mid-market assets and why non-sponsored companies can’t keep pace

The UK mid-market presents a rare structural arbitrage opportunity for international private equity sponsors, corporate acquirers, and institutional investors. Continue reading
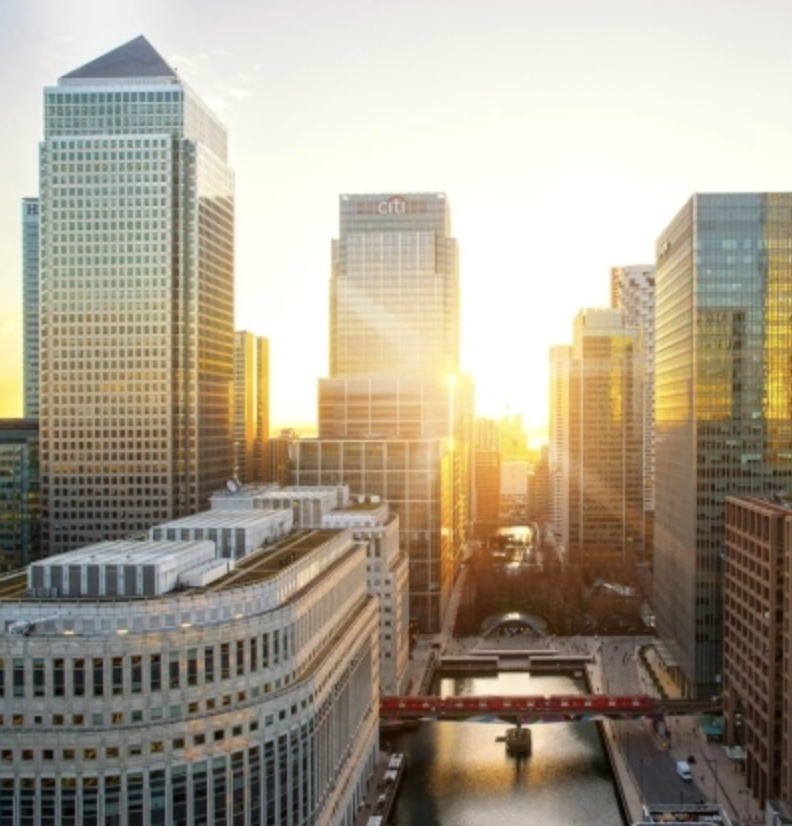
The City of London at dusk from across the Thames: its towers lit up behind the Tower of London, their lights reflected in the river.

Rather than exiting the asset class, institutional investors are sharpening selection criteria.

For over two decades, private equity operated under a seamless implicit contract: Institutional Limited Partners (LPs) committed illiquid capital in exchange for consistent, outsized net alpha over public equity benchmarks. Continue reading

Why Regional Scale & Devolution Are Unlocking the UK’s True Growth Potential

The narrative surrounding UK business growth has long suffered from a London-centric bias. Continue reading

Buy & Hold Models with Decentralized Operations

Buy & Hold buyers—often referred to as permanent capital aggregators or long-term compounders—represent a distinct and powerful asset ownership model in private market M&A. Continue reading

Finding Value in Sub-Scale Assets

In private equity, assets are typically classified across distinct market tiers based on scale, financial performance, and organizational complexity. Continue reading

Evolution, Market Dynamics, and Strategic Implications for LPs, GPs & Mgmt

Independent sponsors—frequently referred to as “deal-by-deal” or “fundless” sponsors—are specialized private equity operators and transaction professionals who identify, structure, and execute corporate acquisitions without relying on a pre-funded, committed commingled fund. Continue reading

Evolution, Market Dynamics, and Strategic Implications for LPs, GPs & Mgmt

Continuation vehicles (CVs)—often referred to as continuation funds—are specialized investment structures established by a private equity sponsor (General Partner or GP) to transfer one or more existing portfolio assets from a maturing primary fund into a newly formed vehicle. Continue reading

As dealmakers for multiple decades, it’s perhaps surprising to find that whilst the world around M&A has changed markedly over the last twenty years, the process of doing deals and in particular due diligence actually has not.

Emails, Excel files, Word files, PDF are the currency of due diligence. With all parties typically cascading a blizzard of partially complete documents all the way through until completion. Continue reading

When I started Independence Capital, we had a singular mission. To be the go-to Private Equity alternative for exit-proven leaders & mgmt teams.

Whilst that remains true in 2025, with still so much potential for the future, another mission is emerging… As drivers of M&A and growth strategies, everyday we engage direct with business owners. Continue reading
Earlier articles

Article 05

FAQ

Throughout the two and a half years since we commenced we have faced a lot of questions. In this article we try and cover the main questions candidates, sellers, advisors and investors have and hopefully help you build the confidence in Independence that some of the country’s leading management teams also have.

After having joined Independence in September 2021, we ask Ben to share some of his experience and observations as a window into the business for future prospective candidates.

Article 03

Deciphering M&A

Navigating the M&A market involves a blizzard of acronyms and a whole new language of terms, phrases, documents and processes. This article serves as a reference base for those wanting to clarify their understanding at any time of day.

Management Buy-In MBI

where an outside Management team acquires the Target Company, with or without a Sponsor

Continue reading
Apologies in advance to those who have landed on this article from an entirely different sort of Google search… because the letters in question here are only MBI otherwise known as “Management-Buy-In”.

It has to be one of, if not the first question, that we often encounter with new teams and leaders considering building for themselves instead of others.

We’ve helped leaders from

  • BGF
  • Mayfair Equity Partners
  • Tyco Electronics
  • ArrowXL
  • Schindler
  • Bunzl
  • thyssenkrupp
  • Nasdaq
  • The Carlyle Group
  • Vitruvian Partners
  • DHL
  • Altamont Capital Partners
  • Jaguar Land Rover
  • M&S

Register interest.

We are always open for business, always looking to support sector-leading talent and add to our ranks operating partners, investors and team members. Tell us a little about yourself and we will be in touch.

Max. file size: 2 MB.
Select Option

Protected by reCAPTCHA: Google’s Privacy Policy and Terms of Service apply.